Approximately 310 businesses are directly affected by the current gambling duty reforms in the UK — around 160 remote betting providers, 95 remote gaming operators, and 55 combined operators. Against that backdrop, new bookmakers continue to enter the market, offering cricket betting to UK punters with fresh interfaces, competitive launch offers, and the promise of something different from the established names. The question for any bettor evaluating a new entrant is not whether the site looks good, but whether it will still be operating in two years under the weight of a regulatory and tax environment that is actively tightening.
I track new market entrants as part of my work, and the pattern I have observed over nine years is consistent: a burst of launches when market conditions appear favourable, followed by a wave of consolidation when costs catch up. The 2025-2026 period has been unusual because new operators are launching into a market where the Remote Gaming Duty has just jumped from 21% to 40% — the largest single increase in UK gambling tax history. That takes either remarkable confidence or a very specific business model.
Who Launched in 2025-2026
The new entrants of 2025-2026 fall into two broad categories. The first is international operators expanding into the UK market — brands with established businesses in other regulated markets (such as European, Latin American, or African jurisdictions) that have applied for UKGC licences to access UK consumers. These operators typically bring existing technology platforms and adapt them for UK regulatory requirements, including responsible gambling tools, identity verification, and advertising standards.
The second category is niche operators targeting specific sports or demographics. Some of the 2025-2026 launches have positioned themselves explicitly as cricket-forward platforms, emphasising deeper cricket market coverage, faster in-play updates, and promotional activity tied to cricket events rather than football. Whether that positioning is genuine or cosmetic depends on the depth of their cricket trading team and the quality of their odds, both of which only become apparent after several weeks of live operation.
Not every launch survives the first year. The cost of customer acquisition in the UK betting market is high — estimates range from 200 to 500 pounds per active depositing customer — and new operators must generate enough volume to cover that cost while also absorbing the new tax burden. Operators that rely heavily on sign-up bonuses to attract initial customers face a painful arithmetic: generous bonuses drive registrations, but each bonus is a cost that the operator must recoup through ongoing activity.
What New Bookmakers Bring to Cricket Betting
The genuine advantage of new entrants is competitive pressure. When a new bookmaker enters the UK market with aggressive cricket odds — pricing match winners tighter than the established operators to attract volume — the market as a whole responds. I have seen established bookmakers adjust their cricket margins within weeks of a new entrant offering noticeably better prices. That competitive dynamic benefits every cricket bettor, even those who never use the new platform.
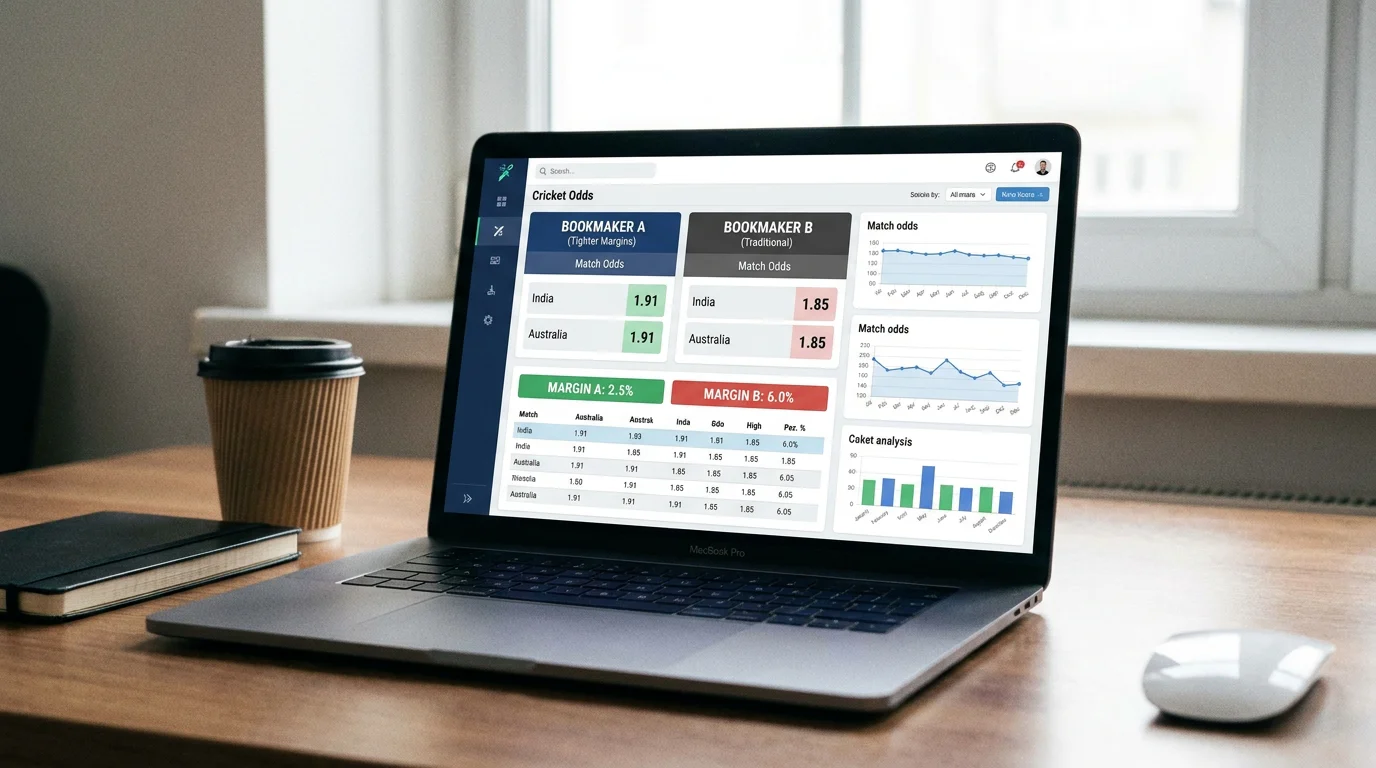
Technology is another differentiator. New operators often launch on modern tech stacks that enable faster bet placement, smoother in-play transitions, and better mobile experiences than platforms built a decade ago and updated incrementally. If you are primarily a live cricket bettor, the speed difference between a modern platform and a legacy one can be material — especially in fast-moving T20 markets where a one-second delay in bet confirmation affects your ability to capture live odds.
Promotional creativity also tends to be higher among new entrants. Rather than the standard “bet 10 get 30 in free bets” template, some new operators offer cricket-specific promotions — enhanced odds on IPL matches, free bets triggered by specific in-match events (a century scored, a hat-trick taken), or loyalty programmes that reward cricket betting volume specifically rather than general activity.
How Tax Reform Pressures New Operators
The Remote Gaming Duty increase from 21% to 40%, effective 1 April 2026, is a structural shock to the industry. Neal Menashe, CEO of Super Group, stated that his company supports reasonable taxation but emphasised that this “very substantial increase should be paired with robust and strict enforcement against non-paying offshore operators” to protect the regulated sector’s investment in jobs, technology, and responsible gambling.
For new operators, the tax increase compounds the already significant cost of market entry. Every pound of gross gaming yield is now taxed at nearly double the previous rate, which means operators need higher volumes or lower costs to maintain viability. The practical consequences for bettors are twofold. First, bonus generosity from new entrants may decline faster than in previous years because the tax burden makes loss-leading promotions less sustainable. Second, operators with thin margins may exit the market within 12 to 18 months, leaving bettors to transfer their activity — and potentially their funds — to surviving platforms.
The government expects the tax reforms to generate an additional 810 million pounds in revenue by 2026-27, rising to 1.16 billion pounds annually by 2030-31. Those figures represent money that is no longer available for operator margins, bonuses, or competitive pricing. New entrants that launched before the tax increase took effect may have modelled their business plan on the 21% rate and now face a fundamentally different economic reality.
Vetting a New Cricket Bookmaker
My due diligence process for any new operator is straightforward, and it starts with the UKGC register. If the operator does not hold a valid UKGC licence, the evaluation ends there. No exceptions.
Beyond licensing, I look at three things. The fund protection level — basic, medium, or high — is listed on the UKGC register and tells you how your money is safeguarded if the operator fails. High protection means your funds are held in a segregated trust account. Basic protection means they are not segregated at all. For a new operator whose long-term viability is uncertain, high protection is not a luxury — it is a necessity.
The depth of cricket markets tells you whether the operator is genuinely committed to cricket or simply listing it to check a box. Open a mid-profile cricket match — a county fixture or a bilateral ODI between mid-ranked sides — and see what markets are available. If the operator offers match winner and nothing else for these fixtures but promises “comprehensive cricket coverage” on their homepage, the coverage is marketing rather than reality.
Customer support responsiveness is the third indicator. Contact the operator with a question about cricket bet settlement before you deposit. The speed and quality of the response tells you how you will be treated when a real issue arises. A new operator that takes 48 hours to answer a pre-registration enquiry will not suddenly become responsive when you have money on the line. For more on how the evolving tax landscape affects pricing and availability, Remote Gaming Duty and cricket betting provides the full regulatory context.
Articles
Created by the "cricketbettingwebsites.com" editorial team.
